Bank said no, or still waiting to hear back? FundMy arranges truck and equipment finance for Australian ABN holders. New or used, from a dealer, an auction or a private seller. Tell us what you are buying and a broker will compare options from our lender panel.
- Who
- ABN holders, Australia-wide
- What
- New or used, dealer or private
- How
- A broker compares lenders for you, at no cost for pre-approval
Rather talk it through? Call 1300 464 805.
Start your pre-approval
Four steps. An initial eligibility check does not affect your credit file. No cost for pre-approval.
What are you financing?
FundMy arranges finance for ABN holders, so we cannot take this enquiry further online. If you do have an ABN, choose Yes to continue. If your ABN is on the way, call 1300 464 805 once it is active.
By submitting you agree FundMy can contact you by phone, SMS or email about this enquiry. See the Privacy Policy of our partner, Equifund Financial Group. A pre-approval is conditional and is not an offer of finance. Protected by reCAPTCHA. The Google Privacy Policy and Terms of Service apply.
Part of Equifund Financial Group. Australian Credit Licence 389328.
Where vehicle and equipment finance gets stuck
Whether you work in transport, construction, farming or a trade, these are the common sticking points. A broker takes your deal to lenders whose criteria suit it.
Bank declined your equipment finance
A no from one lender is not a no from the whole market.
Used gear and private sales
Some lenders consider used gear, auctions and private sales, subject to lender criteria.
Older vehicles and machinery
Lenders weigh age and condition. We tell you early if yours is unlikely to fit.
Equipment finance with a new ABN
Some lenders consider newer ABNs, especially with contracts or income evidence.
Low doc equipment finance
Less paperwork than a standard bank application, subject to lender criteria.
Tight or seasonal cash flow
Repayments can be shaped around how the asset earns, subject to lender criteria.
Truck, vehicle and equipment finance we arrange
Truck and equipment finance is business finance for a vehicle or machine, usually secured against the asset itself. Choose your gear to start, or read more about truck finance.
-
Truck finance
Rigids, tippers, tilt trays and prime movers, new or used.
-
Trailer finance
Flat tops, curtainsiders, tankers and plant trailers.
-
Ute and van finance
Dual cabs, cab chassis and delivery vans used for work.
-
Tractor finance
Tractors, harvesters, sprayers and other farm machinery.
-
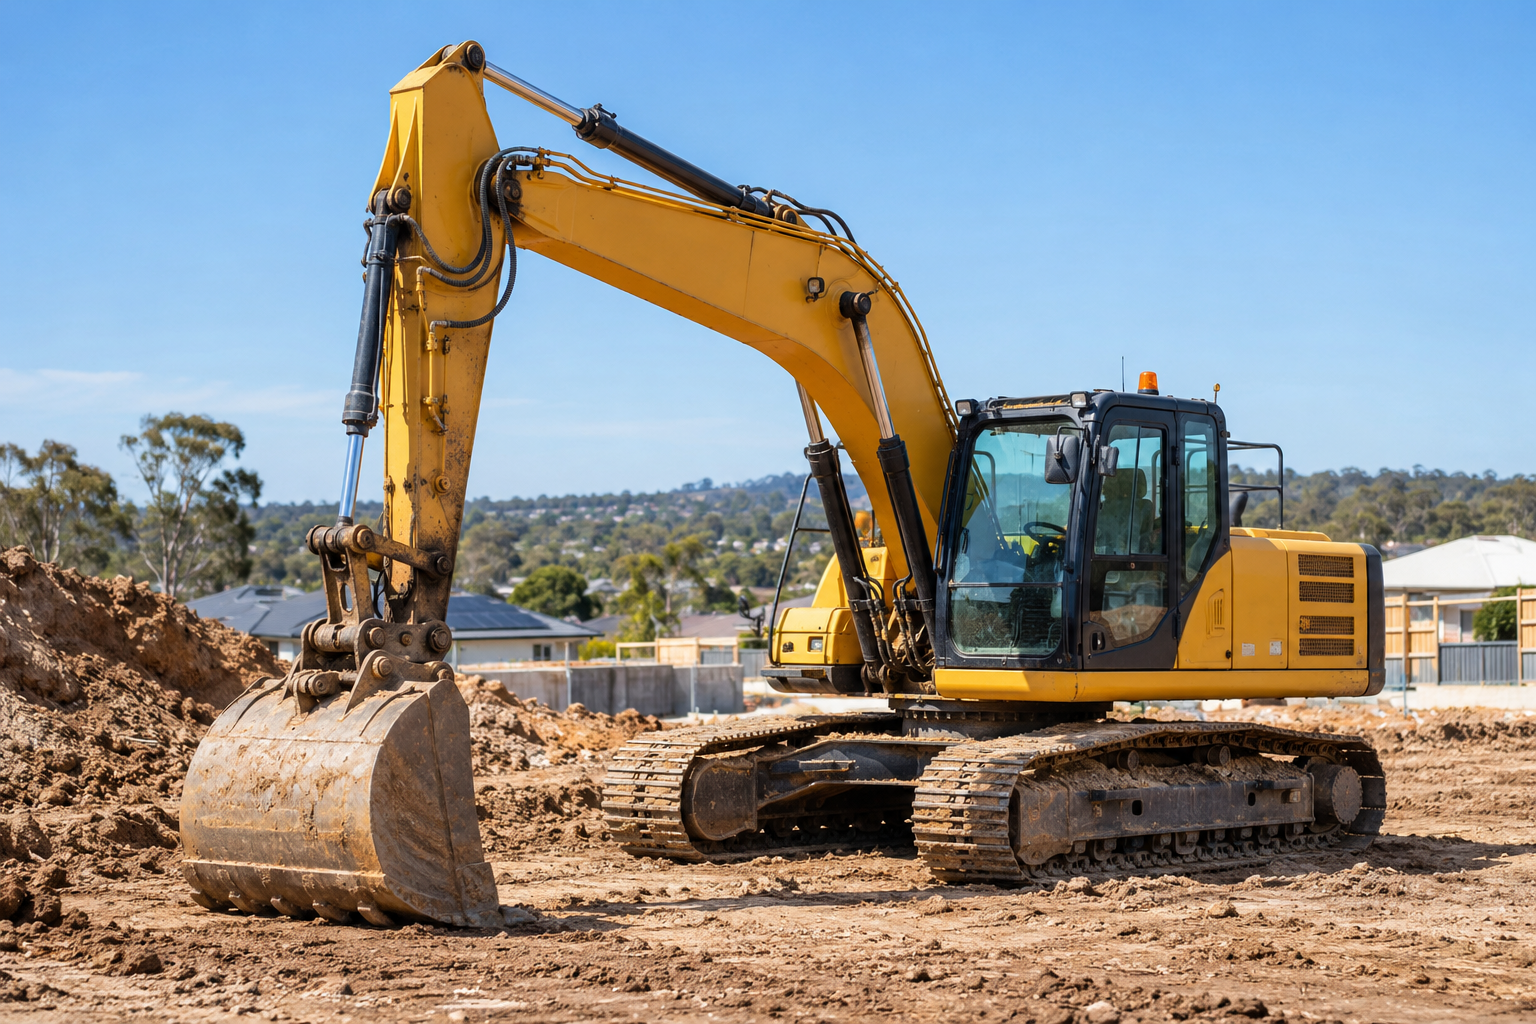
Excavator finance
Excavators, loaders, skid steers and other earthmoving gear.
-
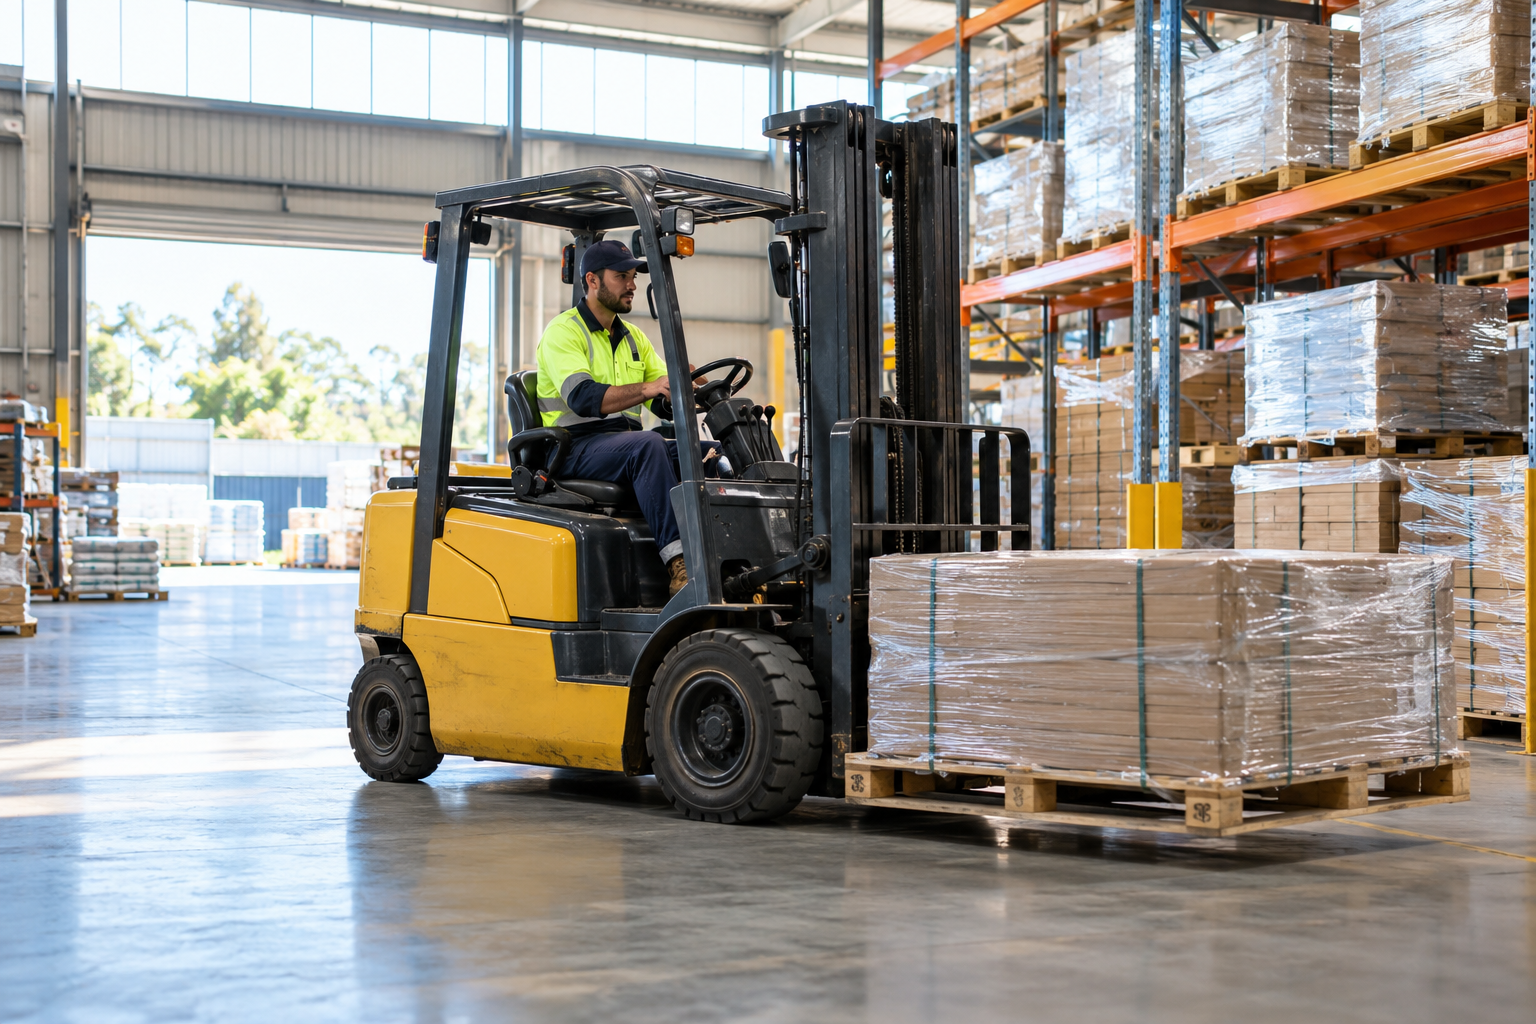
Forklift finance
Forklifts, plus warehouse and workshop equipment.
Compare lenders without applying to each one
Each formal finance application can leave an enquiry on your credit file. With FundMy you find out where you stand first.
Applying to lenders yourself
- A separate application for each lender
- Each one can add an enquiry to your credit file
- A decline means starting again somewhere else
- You compare the offers on your own
Going through FundMy
- One broker to deal with, start to finish
- An initial eligibility check does not affect your credit file
- Your deal goes to lenders whose criteria suit it
- Options laid out side by side, with the costs shown
A formal credit enquiry is only made once you go ahead with a full application.
How truck and equipment finance works with FundMy
You tell us about the gear
Tell FundMy what you are buying and how long your ABN has been active, online or on 1300 464 805.
We work through the lender panel
A FundMy broker calls you, compares lenders and loan types, and seeks a conditional pre-approval.
You choose, we see it through
Pick the option that fits. FundMy deals with the lender and the seller through to settlement.
Like having a mate who knows finance
FundMy is on your side of the deal. We compare your finance options, explain them in plain English and guide you through the purchase, so you can pick the one that suits you.
- We compare your options
- Your broker checks a wide panel of specialist lenders for you.
- We guide your purchase
- A real person to call, from your first question through to settlement.
- No surprises on cost
- You see the rate, fees and charges for each option before you choose.
- Licensed and backed
- Part of Equifund Financial Group, Australian Credit Licence 389328.
FundMy is an Australian finance brokerage for trucks, vehicles and equipment. FundMy is a broker, not a lender.
Getting started
What happens after I send my details to FundMy?
After you send your details, a FundMy broker calls you to talk through what you are buying and how your business is set up. The broker then looks for lenders whose criteria suit the deal and tells you which documents are needed.
What do I need for a pre-approval?
To start a pre-approval you need an active ABN and a rough idea of what you are buying. As it progresses, lenders commonly ask for photo ID, recent BAS or bank statements and details of the truck or machine. Your broker will confirm what the lender needs on your first call.
Will applying affect my credit score?
Starting a pre-approval with FundMy begins with an initial eligibility check, which does not affect your credit file or your credit score. A formal credit enquiry is only made once you go ahead with a full application.
Does a pre-approval commit me to anything?
A pre-approval does not commit you to going ahead with the finance. It is a conditional indication from a lender, not a final decision or an offer of finance. The lender makes its final decision after a full assessment of you and the asset.
Can I get a pre-approval before I have found the truck or machine?
A pre-approval can be started before you have found the exact truck or machine. Tell your broker the type of asset, its likely age and your budget, and they can seek a conditional pre-approval so you know your range before you shop. The lender confirms its decision once the asset and the seller are known, subject to lender criteria.
How long does truck or equipment finance take?
How long truck or equipment finance takes depends on the lender, the asset and how soon the lender has the documents it asks for. Your broker will tell you what is still needed and where your application is up to.
Who is FundMy?
FundMy is an Australian finance brokerage for trucks, trailers, utes, vans, tractors, earthmoving gear and forklifts. FundMy works with ABN holders across Australia, including owner-drivers, operators and fleets. FundMy is part of Equifund Financial Group, Australian Credit Licence 389328.
Is FundMy a lender or a broker?
FundMy is a finance brokerage, not a lender. A FundMy broker takes your application to a wide panel of specialist lenders, explains the options that come back and manages the paperwork through to settlement. The lender you choose provides the finance. FundMy is part of Equifund Financial Group.
Eligibility
My bank declined my truck or equipment finance. Can FundMy still help?
FundMy can often still help after a bank decline, because a no from one lender is not a no from the whole market. Banks decline deals for policy reasons that do not always apply at other lenders, which often affects self-employed operators and contractors who do not fit standard bank policy. With access to a wide lender panel we can often look at options a single bank does not offer. All finance is subject to lender assessment.
Can I get truck or equipment finance with a new ABN?
Truck and equipment finance with a new ABN is possible in some cases. A longer trading history strengthens an application, but we work with lenders who consider newer businesses, especially where contracts or strong income evidence exist.
Is low doc equipment finance available?
Low doc equipment finance is available for eligible businesses and is assessed with less paperwork than a traditional bank application. It can suit ABN holders whose tax returns or financials are not up to date. Eligibility is subject to lender criteria.
Do I need a deposit?
Deposit requirements vary by lender and by deal. Some lenders will consider financing the full purchase price for eligible applicants, while newer ABNs may be asked for a contribution.
Do I need property security?
Property security is typically not needed for equipment finance. Most equipment finance is secured against the asset itself, so you usually do not have to offer property as additional security.
Trucks, gear and sellers
What can I finance through FundMy?
FundMy arranges finance for income-producing assets including trucks, trailers, utes, vans, tractors, harvesters, excavators, forklifts, plant machinery and specialised equipment. The asset can be new or used, from a dealer, an auction or a private seller, subject to lender criteria.
Can I finance a used truck from a private seller?
A used truck bought from a private seller can often be financed, subject to lender criteria. Lenders usually check that the seller owns the truck and that no other finance is owing on it. They may also ask for an inspection or valuation. Your broker will tell you what is needed for your purchase.
Can I finance an older truck or machine?
Older trucks and machinery can often be financed. Lenders set their own limits on asset age, and some specialist lenders weigh condition and earning capacity as well as the year of build, subject to lender criteria. Tell us the make, model and year and your broker will say what is realistic.
Costs and repayments
Does using a finance broker cost more than going to a bank?
Using a finance broker does not have to cost more than going to a bank yourself. A FundMy broker compares options across a wide panel of specialist lenders and shows you the rate, fees and charges for each one before you choose, so you can weigh them against any offer you already have. FundMy is part of Equifund Financial Group and is paid in two ways: the lender may pay a commission for finance we arrange, and a service fee for arranging your finance applies only if your finance settles. Your broker will tell you the service fee amount, and you can ask at any time what commission applies to your finance.
What interest rate will I pay on truck or equipment finance?
The interest rate on truck or equipment finance depends on the lender, the asset, its age, the loan term and your business profile, so there is no single rate. Your broker will show you the rate and the fees and charges for each option before you choose. Rates are set by the lender and are subject to lender criteria.
How does equipment finance work?
Equipment finance lets an Australian business buy income-producing assets such as trucks, machinery and commercial vehicles and pay for them over time, with the asset itself usually acting as security. You choose the asset, a FundMy broker takes your application to a wide panel of specialist lenders, and once the deal settles the lender pays the seller while you make regular repayments. Common structures include a chattel mortgage, a finance lease and hire purchase.
What is the difference between a chattel mortgage, a finance lease and hire purchase?
The difference between a chattel mortgage, a finance lease and hire purchase is who owns the asset during the term. With a chattel mortgage you own the vehicle or machine from the start and the lender holds security over it until the loan is repaid. With a finance lease the lender owns the asset and you pay to use it for an agreed term, usually with a residual value at the end. With hire purchase the lender owns the asset while you pay it off and ownership passes to you after the final payment. The tax and GST treatment differs between them, so check with your accountant before you choose.
What is a balloon payment?
A balloon payment is a lump sum left owing at the end of the loan term, which lowers the regular repayments during the term. It still has to be paid, refinanced or cleared by selling the asset when the term ends. Whether a balloon suits you depends on your circumstances, so talk to your accountant.
Can repayments be structured around seasonal income?
Repayments can often be structured around seasonal, contract-based or uneven income. Seasonal and skip-month structures are common for operators whose income follows harvest, freight or project cycles, subject to lender criteria.
How long are equipment finance terms?
Equipment finance terms commonly run from one to seven years, depending on the asset and the lender.
General information only. It does not take into account your objectives, financial situation or needs. All finance is subject to lender assessment and lending criteria.